Business
ACCA vs. CPA: Which is the Better Career Choice?


Choosing a career in accounting is a big decision. Choosing ACCA vs. CPA depends on your career goals, location, and interests. ACCA (Association of Chartered Certified Accountants) and CPA (Certified Public Accountant) are prestigious qualifications in the accounting world. ACCA offers global recognition, while CPA is more U.S.-focused but highly respected.
ACCA is probably the way to go if you dream of working in multinational companies, travelling for work, or getting involved in international finance. It opens up opportunities all around the world and gives you a chance to work in different countries and industries. On the other hand, if you see your future rooted in the United States, especially in public accounting firms or high-level corporate roles, CPA is the credential you will want to pursue. Well, it’s not just about passing an examination; it’s more like a ticket to senior positions in the U.S. accounting landscape.
What is ACCA?
The Association of Chartered Certified Accountants is a global body for professional accountants. It was established in 1904 and has members in more than 180 countries. ACCA focuses on international accounting standards, making it ideal for those who want a global career. The ACCA qualification covers various topics, including financial management, taxation, auditing, and ethics. To become a member of the ACCA, one has to pass 13 exams, undergo three years of relevant work experience, and an ethics module.
You have the freedom of choosing a variety of exams per year and thus study at your own pace to acquire this prestigious ACCA qualification. You could be employed in various sectors ranging from public practices, corporate finances, consultancy work, or any government jobs and the fact that it has international recognition, among other qualities.
CPA Meaning
CPA stands for Certified Public Accountant. It is a license given to accountants in the United States who pass the CPA exam and meet other state-specific requirements. The CPA credential is highly respected and often required for senior positions in accounting and finance. CPAs are experts in U.S. GAAP (Generally Accepted Accounting Principles), auditing, taxation, and business law.
To become a CPA, you must complete education requirements – usually a bachelor’s degree with specific accounting credits. In addition, you will have to pass the four-part CPA exam and meet any work experience requirements prescribed by the state Board of Accountancy. Some states also require an ethics exam. CPAs work in public accounting firms, corporate finance, government, and non-profits, performing audits, preparing tax returns, and offering consulting services.
Difference Between ACCA and CPA
Knowing the difference between ACCA and CPA can be critical when choosing the right career for yourself. These two qualifications present excellent opportunities with a difference in focus, recognition, and requirement.
| Feature | ACCA | CPA |
| Origin | United Kingdom | United States |
| Global Recognition | Yes, recognized in over 180 countries | Mostly recognized in the U.S., some global reach |
| Focus | International Accounting Standards (IFRS) | U.S. accounting standards (GAAP) |
| Exam Structure | 13 exams | 4 exams |
| Work Experience | 3 years of relevant experience | Varies by state, usually 1-2 years |
| Flexibility | High, multiple exam sessions per year | Fixed exam windows |
| Cost | Generally lower | Generally higher |
| Career Opportunities | Global companies, multinational firms | U.S. firms, public accounting, corporate roles |
| Regulatory Authority | ACCA Global | State Boards of Accountancy |
ACCA vs. CPA: Which has better career advancement opportunities?
Choosing ACCA or CPA may be more important, depending on where you would like to work and your long-term career plans. If you want to work abroad or in countries using IFRS (International Financial Reporting Standards), ACCA is the preferred choice. You can work in more than 180 countries as ACCA enjoys global recognition, which means greater flexibility and varied job opportunities.
However, if you want to practice in the United States or with companies operating on U.S. GAAP, then you must pursue the CPA. This is because it is highly sought after in many senior accounting roles in the U.S.. It is much respected in the U.S. job market compared to a holder of ACCA. Many times, a CPAs earnings power is stronger than that of a member holding the ACCA qualification.
ACCA vs CPA: Which is Easier?
When comparing ACCA and CPA, many students wonder which qualification is easier. The answer depends on your background, study habits, and familiarity with accounting standards.
ACCA offers 13 exams. However, it can be done within a longer time frame, usually across several years. This enables working full-time people or people committed to going at their own pace. Topics such as financial accounting, ethics, and management accounting are covered. However, because of the enormous amount of material, this has been simplified in that students sit for the exams individually.
CPA has four exams only, but they are challenging. The CPA exam concerns U.S. accounting standards, tax laws, and business regulations. The CPA exam would be much easier if you have experience with U.S. GAAP and tax rules in America. But again, having limited windows to the exams and a strict time to complete them may create stress during the process.
ACCA vs CPA Salary
Salary potential is one factor that makes a difference between ACCA and CPA. While both qualifications are competitive in salary, the earning potential varies with location, job role, and industry.
CPAs in the United States can earn higher salaries than members of ACCA. The U.S. places a high value on CPA, and many accounting positions require it to be held by seniors. According to recent surveys, people with a CPA can earn as much as ₹5,800,000 to ₹10,000,000, depending on experience and position. Senior CPAs or managerial positions would earn more; some could go beyond ₹12,500,000 annually.
Members of ACCA also earn competitive salaries, especially in countries that recognise the qualification. In the UK, the average salary of an ACCA professional can be anywhere between ₹4,000,000 to ₹7,000,000 annually, while higher for more senior positions. In other countries, the salaries depend on the local job market and demand for ACCA-qualified professionals.
ACCA and CPA Eligibility
Eligibility requirements for ACCA and CPA vary, and it is important to know them before choosing your career path.
One must have completed secondary education, equivalent to going through high school. Most students begin ACCA right after school, though having a bachelor’s degree is beneficial, as you would thus avoid some of the exams. ACCA is very flexible, and it can be joined regardless of educational background. To be a full member, One must pass 13 exam papers, achieve three years of relevant work experience, and complete an ethics module.
The requirement to become a CPA is stricter. You must hold at least a bachelor’s degree with specific numbers of accounting and business credits. Most states require 150 credit hours, exceeding a typical bachelor’s degree. This means you must do additional coursework or acquire a master’s degree. In addition, you must pass the four-part CPA exam and meet the various requirements of work experience. Some states require an ethics exam, so not all are the same.
ACCA vs CPA Difficulty Level
A significant factor for choosing between the two is the difficulty level of the ACCA and CPA exams. Although challenging, the two qualifications are difficult in different ways.
ACCA has 13 exams that cover a wide range of topics. The exams test your knowledge in financial management, taxation, auditing, and ethics. Although the exams are challenging, the flexibility to take them at your own pace makes it manageable. ACCA’s broad curriculum means you must master many subjects, but you can focus on one exam at a time.
The CPA exam comprises four sections: Auditing and Attestation (AUD), Business Environment and Concepts (BEC), Financial Accounting and Reporting (FAR), and Regulation (REG). These are very hard and demand deeper knowledge of the U.S. accounting standards and regulations. Strict time limits with limited testing windows make the examination even more intensive. Yet, it seems more straightforward with just four exams than ACCA’s 13 exams.
ACCA vs CPA Job Profile
Job profiles of ACCA and CPA professionals vary based on the focus and recognition of the qualification.
Members of ACCA work in multinational companies, financial institutions, consulting firms, and government agencies. Their roles include financial analyst, auditor, tax consultant, and management accountant. Due to global recognition, professionals can work in various countries and industries. The focus on international accounting standards makes members of ACCA valuable for companies that operate across borders.
CPAs work in public accounting firms, corporate finance departments, government, and non-profits. They conduct audits, prepare tax returns, and provide consulting services. CPAs often hold senior positions such as financial controller, CFO, and audit manager. In the U.S., the CPA credential is required for many roles, especially in public accounting and auditing.

Risk teams inside Indian banks, NBFCs, and asset managers have grown fast over the last few years, and the question of what is FRM comes up constantly among commerce graduates and working finance professionals trying to pick a credential that actually matches this hiring demand. The Financial Risk Manager designation, awarded by the Global Association of Risk Professionals (GARP), sits at the centre of that conversation, and a financial risk management course built around it has become one of the more direct routes into risk roles at Indian financial institutions. This piece walks through what the credential covers, how the exams are structured, what it costs in India, and where graduates commonly land, using figures current as of August 2026.
What Is FRM as a Credential
Before comparing course formats or study plans, it helps to be clear on what is FRM actually certifying and who grants it.
FRM stands for Financial Risk Manager, a certification governed by GARP, the Global Association of Risk Professionals, based in the United States. Unlike accounting credentials built around reporting or audit, FRM centres on identifying, measuring, and managing risk inside a bank, fund, or corporate treasury. There is no entry requirement to register for the exam itself, which means a final year student or someone several years into a finance career can both sit for it without a degree check at the registration stage. The charter, however, only comes after passing both exam parts and completing 2 years of relevant full time work experience in risk management or a closely related field, submitted for approval within 5 years of clearing Part 2.
How a Financial Risk Management Course Is Structured
A financial risk management course follows the two part exam structure GARP sets, and knowing that structure upfront makes it easier to plan study time around a job or degree programme.
Part 1 runs for 4 hours across 100 questions and covers four topic areas: Foundations of Risk Management at 20 percent, Quantitative Analysis at 20 percent, Financial Markets and Products at 30 percent, and Valuation and Risk Models at 30 percent. Part 2 runs for 4 hours across 80 questions, spread across Market Risk Measurement and Management at 20 percent, Credit Risk Measurement and Management at 20 percent, Operational Risk and Resilience at 20 percent, Liquidity and Treasury Risk Measurement and Management at 15 percent, Risk Management and Investment Management at 15 percent, and Current Issues in Financial Markets at 10 percent.
Exam Format and Test Centres
Both parts are computer based, multiple choice, and delivered at PSI test centres, with no negative marking for wrong answers. Part 1 allows roughly 2.4 minutes per question, while Part 2 gives about 3 minutes per question, a pace most candidates only get comfortable with after several timed mock attempts.
Fees for Indian Candidates
A financial risk management course budget in India needs to account for GARP’s own fee structure, not just coaching costs. The first time enrollment fee, which covers Part 1 only, runs USD 400. Early registration for the exam itself costs USD 600 per part, rising to USD 800 per part under standard registration. Candidates who register early for both parts and avoid the standard window save a meaningful amount compared to those who wait.
Study Duration and Sequencing
Most candidates preparing through a structured financial risk management course spend 4 to 6 months on Part 1 and a similar stretch on Part 2, though this varies with prior exposure to quantitative finance. GARP does not require Part 1 and Part 2 to be attempted in a fixed order relative to each other in terms of preparation approach, though a candidate must clear Part 1 before attempting Part 2.
GARP Code of Conduct
Alongside the technical syllabus, GARP holds every candidate and charter holder to a Code of Conduct covering professional integrity, competence, and conflicts of interest. Continued use of the FRM designation after certification depends on staying compliant with this code, which coaching providers in India tend to cover briefly during orientation sessions rather than treating it as a standalone paper.
Why the Credential Fits the Indian Job Market
| Factor | Detail |
| Recognised employers | Banks, NBFCs, credit rating agencies, asset managers, consulting firms |
| Typical entry roles | Credit risk analyst, market risk associate, operational risk analyst |
| No fixed prerequisite | Registration open to students and working professionals alike |
| Global body | GARP, headquartered in the United States, exam delivered worldwide |
Indian risk hiring has leaned harder into candidates who can speak the language of value at risk, stress testing, and credit exposure limits without needing months of on the job translation, and a financial risk management course built around the FRM syllabus is designed to produce exactly that vocabulary. Banks running Basel compliant risk functions, NBFCs building out credit risk desks, and rating agencies assessing corporate exposure all draw from a similar talent pool, which keeps demand fairly broad across sub sectors rather than concentrated in one type of employer.
A few practical points worth noting for someone weighing this route:
- The credential travels well outside India too, since GARP administers the same exam globally, which matters for candidates eyeing risk roles abroad later in their career
- Working professionals do not need to pause a job to register, since there is no minimum degree or experience requirement at the registration stage
- The 2 year work experience requirement for the charter can be completed after passing both exam parts, so someone can clear the exams first and build qualifying experience afterward
Conclusion
Financial risk management as a career path in India increasingly runs through a credential most people first encounter as an acronym, and a proper financial risk management course clears up what is FRM actually asking a candidate to learn: how to measure, price, and manage risk across markets, credit, and operations. The two part structure, GARP’s Code of Conduct, and the August 2026 fee schedule outlined here give a realistic starting point for anyone comparing this route against other finance credentials. Zell Education’s FRM guidance can help map a study plan around a college schedule or an existing job, whichever stage a candidate is starting from.

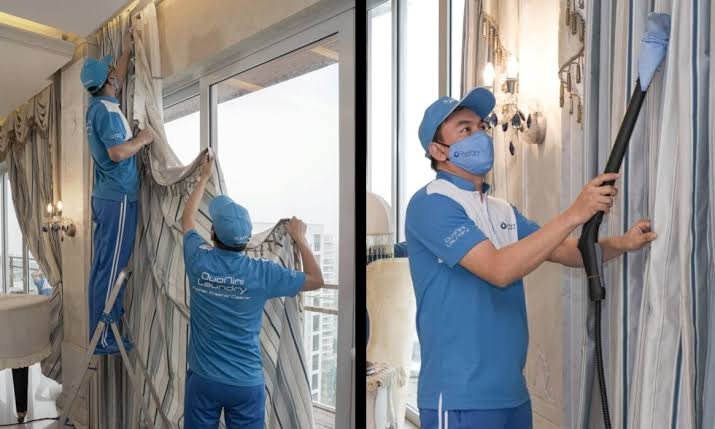
A clean home is not just about sparkling floors and dust-free shelves. Soft furnishings such as curtains and sofas play an equally important role in creating a comfortable and healthy living environment. Over time, they accumulate dust, allergens, bacteria, pet dander, body oils, and unpleasant odours that regular household cleaning simply cannot remove. At Duo Nini, we provide professional curtain cleaning service and sofa cleaning solutions that help homeowners and businesses maintain cleaner, fresher, and healthier indoor spaces.
As one of Singapore’s most trusted cleaning specialists, Duo Nini has built a strong reputation for delivering high-quality cleaning services backed by experienced technicians, professional equipment, and outstanding customer service. Whether you need routine maintenance or a deep clean before moving house, our team is committed to providing results that exceed expectations.
Our professional curtain cleaning service is designed to remove years of accumulated dust and contaminants while preserving the quality of your curtains. Curtains act like large air filters, trapping airborne particles from open windows, air conditioning systems, cooking fumes, and everyday household activities. Over time, these particles become deeply embedded within the fabric, affecting both appearance and indoor air quality.
At Duo Nini, every curtain cleaning project begins with a careful assessment of the curtain material, level of soiling, and cleaning requirements. We offer both on-site curtain steam cleaning and off-site curtain dry cleaning, allowing us to recommend the safest and most effective solution for every fabric type.
Our on-site steam cleaning service is ideal for routine maintenance and homes that require minimal disruption. Using commercial-grade high-temperature steam equipment, we effectively remove dust, bacteria, allergens, and odours while refreshing the curtain fabric. Since the curtains remain hanging throughout the process, homeowners enjoy a fast and convenient cleaning experience.
For delicate fabrics, premium drapes, or heavily soiled curtains, our off-site dry cleaning service provides a more thorough treatment. Our technicians carefully remove the curtains, transport them to our specialised cleaning facility, professionally clean them using fabric-appropriate methods, inspect them for quality, and reinstall them once the process is complete. This ensures your curtains are returned clean, fresh, and well cared for.
Alongside our curtain expertise, Duo Nini also provides professional sofa cleaning services for fabric, leather, and upholstered furniture. Sofas are among the most
frequently used pieces of furniture in any home, making them susceptible to stains, food spills, dust mites, pet hair, bacteria, and accumulated dirt.
Our sofa cleaning process combines industrial-grade vacuuming, fabric-safe cleaning solutions, deep extraction, and high-temperature steam cleaning to remove embedded dirt while helping restore the appearance of the upholstery. For leather sofas, we use specialised cleaning and conditioning products that gently remove dirt while preserving the leather’s natural texture and finish. Every cleaning method is carefully selected to suit the specific material, ensuring safe and effective results.
Beyond residential properties, Duo Nini also serves offices, hotels, schools, retail outlets, restaurants, and commercial buildings across Singapore. Our experienced team is equipped to manage projects of every size while maintaining the same high standards of workmanship and professionalism that our customers have come to expect.
What truly sets Duo Nini apart is our dedication to customer satisfaction. From your initial enquiry to the completion of every project, we strive to provide prompt communication, transparent pricing, punctual service, and meticulous attention to detail. Our goal is not simply to clean your furnishings, but to extend their lifespan and create a healthier environment for your family, employees, or customers.
If you are looking for a reliable curtain cleaning service or professional sofa cleaning in Singapore, Duo Nini is ready to help. With years of industry experience, skilled technicians, and a commitment to quality, we continue to be the trusted choice for homeowners and businesses seeking exceptional cleaning services. Contact Duo Nini today and experience the difference that professional care can make for your curtains, sofas, and indoor living spaces.

Managing loans manually has become increasingly difficult in today’s fast-paced financial environment. Lenders are expected to process applications quickly, maintain accurate borrower records, track repayments, ensure compliance, and reduce risks—all while delivering a seamless customer experience. This is where loan software for lenders plays a vital role.
Modern lending institutions, NBFCs, banks, fintech companies, and private lenders are turning to digital solutions to automate and simplify their operations. From loan origination to repayment tracking and recovery management, advanced software solutions streamline every stage of the lending cycle. Combined with powerful Collection Software, these systems help lenders improve efficiency, reduce manual errors, and maximize profitability.
The Growing Need for Loan Automation
Traditional loan management methods often involve spreadsheets, paperwork, and disconnected systems. These outdated processes can lead to delays, data inaccuracies, poor communication, and compliance issues. As customer expectations continue to rise, lenders need smarter technology to stay competitive.
This is why many financial organizations are investing in loan software for lenders. The software automates repetitive tasks, centralizes borrower information, and enables lenders to manage multiple loan portfolios efficiently. Instead of relying on manual calculations and paperwork, lenders can focus on improving customer service and growing their business.
Simplified Loan Origination Process
One of the biggest advantages of using loan software for lenders is the automation of the loan origination process. The software allows borrowers to submit applications online, upload documents digitally, and receive faster approvals.
The system automatically verifies borrower information, performs credit assessments, and calculates loan eligibility. This significantly reduces processing time and minimizes human intervention. Lenders can review applications in real time and make faster decisions, improving customer satisfaction.
Automated workflows also ensure that every application follows a standardized process, reducing the risk of errors and inconsistencies.
Centralized Borrower Management
Managing borrower data manually can become overwhelming, especially for lenders handling large loan volumes. Modern loan software for lenders provides a centralized platform where all borrower information is stored securely in one place.
Lenders can access customer profiles, repayment schedules, communication history, loan agreements, and financial documents instantly. This improves transparency and enables staff members to provide faster support to borrowers.
A centralized system also enhances collaboration between departments, ensuring that loan officers, collection teams, and management have access to accurate and updated information.
Automated Repayment Tracking
Tracking repayments manually is time-consuming and prone to mistakes. Missed payments, delayed updates, and incorrect calculations can negatively impact both lenders and borrowers.
With loan software for lenders, repayment tracking becomes fully automated. The system generates repayment schedules, calculates interest, tracks due dates, and updates payment statuses automatically.
Borrowers receive reminders through SMS, email, or mobile notifications before payment deadlines. Automated reminders reduce missed payments and improve collection rates.
The software also allows lenders to track overdue accounts in real time and identify high-risk borrowers quickly.
Improved Collections with Collection Software
Recovering overdue payments is one of the most challenging aspects of loan management. Manual collection processes often lead to inefficiencies, communication gaps, and lower recovery rates.
This is where advanced Collection Software becomes extremely valuable. Integrated Collection Software helps lenders automate follow-ups, prioritize delinquent accounts, and improve recovery performance.
The system can automatically send payment reminders, escalation notices, and settlement offers based on predefined rules. Collection agents can track borrower interactions, schedule follow-ups, and monitor recovery progress from a single dashboard.
By using Collection Software lenders can reduce collection costs, improve customer communication, and recover payments more efficiently without creating negative borrower experiences.
Better Compliance and Risk Management
Regulatory compliance is critical in the lending industry. Financial institutions must follow strict guidelines related to data security, reporting, customer verification, and lending practices.
Modern loan software for lenders helps organizations maintain compliance by automating documentation, audit trails, and reporting processes. The software ensures that all borrower information is stored securely and that every transaction is properly recorded.
Risk management tools within the system also help lenders identify potential defaults early. Advanced analytics and credit scoring features allow lenders to assess borrower risk more accurately before approving loans.
This reduces the likelihood of bad debts and improves overall portfolio quality.
Enhanced Customer Experience
Customer experience plays a major role in the success of any lending business. Borrowers today expect quick approvals, transparent communication, and convenient payment options.
Using loan software for lenders, organizations can provide a seamless digital experience from application to repayment. Borrowers can apply online, upload documents digitally, view loan details, and make payments through multiple channels.
Automated communication keeps borrowers informed throughout the loan lifecycle. Faster responses and transparent processes help build trust and improve customer retention.
Integrated Collection Software also ensures that collection activities remain professional and organized, reducing borrower frustration during repayment follow-ups.
Real-Time Reporting and Analytics
Accurate reporting is essential for making informed business decisions. Manual reporting methods often take time and may contain inaccuracies.
Modern loan software for lenders offers real-time dashboards and detailed analytics that provide insights into loan performance, repayment trends, overdue accounts, and collection efficiency.
Lenders can monitor key performance indicators, evaluate portfolio health, and identify areas for improvement instantly. Data-driven insights help businesses make smarter lending decisions and improve operational efficiency.
Reports generated by the software also support compliance audits and management reviews.
Scalability for Growing Lending Businesses
As lending businesses grow, managing larger loan portfolios manually becomes increasingly difficult. Expanding operations without the right technology can lead to operational bottlenecks and service delays.
Scalable loan software for lenders allows businesses to handle increasing loan volumes efficiently without significantly increasing operational costs. Whether managing personal loans, business loans, vehicle loans, or microfinance lending, the software adapts to changing business needs.
Integrated Collection Software also scales with business growth, enabling lenders to manage larger recovery operations effectively.
Conclusion
The lending industry is rapidly evolving, and digital transformation has become essential for success. Implementing reliable loan software for lenders enables financial institutions to automate operations, reduce manual workloads, improve compliance, and deliver better customer experiences.
From loan origination and repayment tracking to reporting and collections, the software simplifies every stage of loan management. When combined with advanced Collection Software, lenders can improve recovery rates, reduce operational costs, and strengthen borrower relationships.
As competition in the financial sector continues to grow, adopting modern lending technology is no longer optional—it is a strategic necessity for lenders looking to improve efficiency, profitability, and long-term growth.

What Is Financial Risk Management Course in India

Professional Curtain Cleaning & Sofa Cleaning in Singapore by Duo Nini

How Loan Software for Lenders Simplifies Loan Management
Complete Beginner’s Guide to What Is CFD Trading in 2025
Latest Boys Fashion: Trends Every Young Man Should Follow
The 5 Best AI Tools for Image & Video Creation in 2025
What Is Financial Risk Management Course in India
Professional Curtain Cleaning & Sofa Cleaning in Singapore by Duo Nini
How Loan Software for Lenders Simplifies Loan Management

The Role of Greenhouse Gas Reporting Software UAE in Corporate Reporting

The Growing Importance of Explosives Trace Detector Systems in Smart Security
-
Business1 year ago
Complete Beginner’s Guide to What Is CFD Trading in 2025
-
Lifestyle2 years ago
Latest Boys Fashion: Trends Every Young Man Should Follow
-
Business1 year ago
The 5 Best AI Tools for Image & Video Creation in 2025
-
 Business10 months ago
Data Science Classes for Beginners with No Coding Background
-
 Technology8 months ago
Top 7 Data Science Courses for Job-Ready Analytics and AI Roles in 2026
-
 Technology8 months ago
SEO by HighSoftware99.com – Rank Higher Today
-
 Technology1 year ago
The Techno Tricks: Unlocking the Future with Cutting-Edge Innovation
-
 Business9 months ago
Why Economics Students are Re-evaluating Traditional Study Methods in 2026